Showing posts with label UK. Show all posts

Friday, 25 November 2016

The scale of the European investment crisis and why it matters

Investment in Europe, both public and private, dropped dramatically following the international financial crisis, and in its aftermath growth has been weak in some countries and non-existent in others. The lack of investment growth is particularly worrying in peripheral countries where it hampers the chances of future economic and productivity growth, as well as limiting employment expansion.
Just how steep was the drop?
It’s pretty serious. The Eurozone economy is now about six per cent larger than it was ten years ago, but the real value of investments is still six per cent below its 2006 levels. When compared to the pre-crisis peak in the first quarter of 2008 the drop is even larger, about twelve per cent.
The investment crisis hit the peripheral countries — Greece, Italy, Portugal and Spain — particularly hard. The real value of investments in Portugal, Spain and Italy is about 30 per cent smaller than ten years ago, while that of Greece shrank by 70 per cent.
Were it not for the contraction of investment, the Portuguese economy would have expanded by five per cent in the last ten years instead of contracting; the Italian output would have been flat rather than six per cent smaller and the Greek economy would be 8 per cent, rather than 24 per cent, smaller than ten years ago. And this is without taking into account the multiplying effect of investment on consumption and productivity.
Most peripheral countries are now showing signs of recovery. In Spain, gross fixed capital formation rose by 17 per cent since its lowest point in 2013. In Italy the sector started expanding again in 2014, but only marginally, while in Portugal investment started declining again after a couple of years of recovery. All of them have a long way to go to return to ‘normality’.
The drop is partly due to the collapse of the housing bubble in some of those countries, particularly Spain. And “a swift return to those investment levels would not to be expected or desired” writes a McKinsey report aptly titled “Investing in growth”.
In Greece, investment in dwelling dropped in real terms from €5.3bn ten years ago to just €300m now, a staggering 94 per cent drop. Investment levels in dwellings were halved in Portugal and Spain.
But the drop was not confined to dwellings. Investment in other buildings including factories and schools also fell, as did spending in buying and updating machinery and equipment.
Experts are growing concerned
Economists agree that it matters a great deal, and say it could actually be instrumental to European stability.
The lack of investment growth “is a big concern in terms of demand but also in terms of productivity and potential growth” explains Sebastian Barnes, a senior economist at the OECD and head of its EU desk.
“Low investment reduces aggregate demand, thus lowering short-term growth, and it also hampers medium-term growth through its effect on the capital stock” writeMarco Buti and Philipp Mohl from the Economic and Financial Arm of the European Commission.
“The EU investment crisis means obsolescence of capital, losses in terms of technological advances and potential constraints affecting an effective reallocation of resources” warned a report from the European Investment Bank.
So why is investment not growing?
There is little appetite to invest when demand – both domestic and international — is sluggish, banks are burdened with a heaping pile of bad debts, alternative forms of lending are limited, and uncertainty about the future is high as is the case in peripheral Europe, to varying degrees.
It’s a vicious circle. Until investment growth doesn’t pick up, demand is likely to remain sluggish and the proportion of non-performing loans has little chances of declining. As a result, confidence is unlikely to pick up: “a low growth trap”, as the OECD put it.
The way out? Reforms
In order to escape the low-growth trap and foster investment, governments should work on making their countries more attractive to investors and make investments easier by introducing labour and product-market reforms. This has been repeatedly advocated by both the IMF and the OECD.
These countries did start a process of reforms to improve their competitiveness, including major labour market reforms in Italy and Spain, albeit with little uplift in investments so far. Mr. Barnes encourages governments to do more, particularly in terms of product reforms.
Another major challenge is the financing glut
Stacked with mountainous bad debts, banks can hardly focus on financing new investments. The Capital Market Union, the European project aimed at developing alternative sources of finance firms across the member states, would come in handy at this time. But after the UK voted to leave the EU the project slowed down, to say the least.
Shaking up the status quo
European countries, particularly in the periphery, cut public investment following the financial crisis. As conditions improved, many governments began adopting looser policies, but this barely affected spending in investment. Instead, taxes were cut and administrations focused on encouraging consumption. But, says Barnes, these initiatives won’t do much to promote longer-term growth.
One way public investment could be bolstered is by rethinking the European Union’s fiscal rules and exclude net investment from the spending limit of three per cent of GDP. This is a controversial suggestion, but as they say sometimes stirring the boat is the only way to keep it from sinking.

Why Europe’s banks will never be the same again

European banks have been shrinking since the financial crisis, dwindling both in terms of their market value, number of branches and staff. Their fortunes have suffered and profits fallen as a result of stricter regulations, general economic weakness and low interest rates.
It’s unlikely that they will ever be the same again. All the more so as the decline in Europe’s over-reliance on banks could present new opportunities for the region to develop much-needed alternative financing channels.
Financial companies lost one trillion euros in market value
Since August 2007 the 471 financial companies that form Datastream’s financials equities sector lost over one trillion euros in market value. That’s the equivalent of Spain’s yearly GDP wiped out.
No other EU sector suffered a comparable loss, not even Oil & Gas contending with low oil prices.
Back in 2007, financial service companies were by far the largest EU Datastream sector by market value, roughly 64 per cent larger than the consumer goods sector. Now they are about the same and the latter was even briefly bigger in the aftermath of Britain’s EU’s referendum.
The worst performing sector in the EU since 2007? Banks
Datastream’s EU financials index has halved since its pre-crisis peak. By comparison, healthcare and consumer goods stocks indices are 70 per cent higher.
This is truly a pan-European story. Bank stocks are traded at less than 40 per cent of their August 2007 prices across all major European countries. German and Italian banks are traded at about 15 per cent their 2007 levels, while the Portuguese banks index is at an incredibly low 2 per cent of its pre-crisis price.
Back in 2007, there were 15 banks among the largest companies by market value of the European Stoxx 600. Today they are down to five.
Thousands of job cuts and axed branches
In 2015 there were more than 27,000 fewer bank branches in the Eurozone than in 2007, a drop of 13 per cent. There were 212,000 fewer people employed in banking, a 10 per cent drop since before the crisis according to the ECB.
The downsizing was particularly dramatic in France – where the number of banks halved to 360 – and Spain where it was exacerbated by a poor recovery in overall employment.
The largely fragmented German banking sector was not left unscathed. In July this year it counted 1,745 credit institutions, 14 per cent less than in the same month in 2007.
The European banking sector needed to downsize
Up until the 1990s the EU banking sector was comparable in size to other advanced countries. But soon after it “became extraordinarily large” and now “Europe is home to the world’s largest banking system” according to Sam Langfield and Marco Pagano, authors of ‘Is Europe overbanked?’.
Behind this disproportionate growth were government policies:
“Eurozone banks (..) benefited from a greater reduction in funding costs owing to government support than US banks” they write.
This meant that alternative forms of funding were hard to come by and to this day they are notoriously weak. The EU’s equity market is about half the size of that of the US, its securitisation market is less than a quarter – this is despite their economy being roughly the same size.
Time for change
According to Langfield and Pagano, the downsizing of the banks has created a slack which “security markets have partly taken up”.
It’s about time. Mario Draghi, president of the ECB, has said that “it’s better to have a plurality of channels financing the real economy than to rely on just one”. And indeed, the point of a Capital Market Union is to “diversify and amplify sources of finance”.
But there is change in the horizon. Langfield and Parano believe the shift from the old bank-based model to market-based finance “is likely to prove structural”.

Four key facts about grammar schools – in charts

Theresa May, Britain’s prime minister, announced on Friday the expansions of grammar schools.

Currently there are just 163 grammar schools in England and Wales totalling 167,000 pupils, or 5 per cent of all state secondary pupils.Back in the 1960s there were nearly 1,300 schools and around one quarter of all state secondary pupils attended them.
Most of the drop happened in the 1970s when Margaret Thatcher – then education secretary – approved the closure of most grammar schools.
The South East has the highest proportion of children attending grammar schools – 12 per cent, according to a report by the House of Commons Library, while there are no grammar schools in the North East. The region accounts for 36 per cent of all grammar school students, with the vast majority in Kent.
Grammar schools are state-funded secondary schools which select pupils based on their ability and academic achievements. The academic results of grammar school pupils are notoriously much higher than those of pupils based in other mainstream schools.
Although plans to approve a fresh wave grammar schools are being floated on grounds of boosting social mobility, the evidence shows that grammar pupils are actually less likely to come from disadvantaged backgrounds.
Various studies have shown that grammar schools have a smaller proportion of pupils eligible for free school meals – a proxy for social deprivation – than other schools.
According to a Sutton Trust report “in local authorities that operate the grammar system, children who are not eligible for free school meals have a much greater chance of attending a grammar school than similarly high achieving children (as measured by their Key Stage 2 test scores) who are eligible for free school meals”.
Other studies have shown that grammar schools have larger proportions of pupils of Asian and Chinese origin, but “grammar schools have lower proportions of Black pupils than other schools”.
Although new or expanding grammars will be required to take a minimum share of pupils from lower income households, many in the educational establishment – such as Ofsted head Sir Michael Wilshaw – have expressed reservations about the plans.

Friday, 10 June 2016

Discontent among UK teachers drives recruitment crisis

Discontent among UK teachers drives recruitment crisis

“Start a new rewarding career this September” writes the Department for Education on a website inviting people to become teachers, “places are still available.” They might be available for a long time, if data on teachers’ satisfaction, recruitment and retention is to be considered.
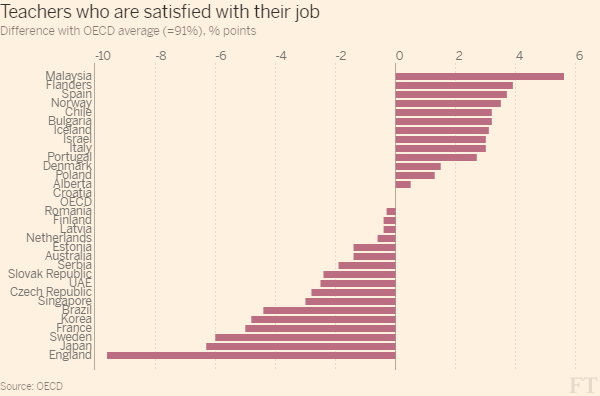
UK teachers were the least satisfied in an OECD survey of 5 million teachers across 34 advanced economies carried out in 2013. That’s ten percentage points less satisfied than the average.
And the mood seems to have deteriorated
Last year 67 per cent of teachers reported declining morale, and more than half were considering leaving the profession.
These days an even higher proportion of teachers – 83 per cent – is thinking of quitting according to research by the Association of Teachers & Lecturers (ATL) released in March.
Heavy workload
“Workload is a real issue” says Dr Mary Bousted, general secretary of ATL, in an interview with the Financial Times. “Experienced teachers are leaving the profession because they can’t stand the workload and the stress anymore.”
This finding is confirmed by teachers’ surveys which show that the volume of workload is the key reason for teachers planning to leave the profession.
Teachers in England spend more time in the classroom than most of their international peers. Moreover, in England teachers spend an average of 14 hours per week planning lessons and marking homework, that’s three hours longer than in the average of the OECD.
UK teachers are also burdened by “bureaucratic nonsense”, as Dr Bousted put it, referring to the time spent filling forms for accountability reasons.
Although the government has attempted to cut down on the workload by, amongst other measures, reducing the number of compulsory reports and plans for inspectors, the new curriculum and new policies “are placing a significant workload on teachers for the next 2 years” schools minister Nick Gibb admitted in a speech to the Association of School and College Leaders last month.
A curriculum which is “not fit for purpose”
The aim of the government’s curriculum reforms is to allow “all children, not just the offspring of the wealthy and privileged [to be] able to write fluent, cogent and grammatically correct English”.
But the majority of the teachers, and 70 per cent of head teachers, believe it is not fit for purpose. And three in four teachers believe that the policies behind the school curriculum and pupil assessments were narrow and uncreative.
“We have primary and secondary school curriculum that is highly inappropriate and ridiculously difficult”, says Dr Bousted. “A whole range of education experts, and teacher professionals, are opposed to the current curriculum and tests’”.
Other reforms were also poorly received by most teachers
Most teachers didn’t think that the proposed baseline tests for reception pupils would give a reliable measure of their progress.
And only a minority of British teachers (17 per cent) thought that turning schools into academies – independent, state-funded schools, which receive their funding directly from central government – would improve standards.
Both proposals were scrapped.
Government U-turns
So with reforms being introduced and scrapped it’s hardly surprising that the rapid pace of policy changes is why a third of teachers are considering leaving the profession.
Leaked tests being published and the delay in publishing a syllabus also add to the ‘storm of discontent’, as Dr Bousted called it, affecting UK teachers.
This leads us to a teacher shortage
Is the teachers’ discontent only temporary and linked to the “chaotic” implementation of reforms or is it a sign of more structural problems? It’s hard to say. Meanwhile, the teaching roles advertised are likely to remain unfilled.
Indeed in 2013 UK teachers had fewer years of working experience than most of their OECD counterparts. They were also generally younger, which suggests a lower retention rate within the profession.
In 2014, nearly 36,000 qualified teachers left the profession before retiring, 13 per cent more than in the previous year.
The number of vacancies more than tripled from 500 in 2011 to well over 1,700 in 2014.
This year recruiting targets were met in just three subjects: history, English and physical education. The remaining fourteen subjects faced a shortage of teachers including seven per cent gap in Maths, according to the National Audit Office.
Widening discontent
“Interestingly now, opposition is also coming from parents” says Dr. Bousted. And there are plenty of signs of this happening.
The recent strikes over the new SATs test, with nearly 69,000 people signing apetition to scrap it, point to discontent spreading beyond the profession.

Brexit and the Capital Markets Union

Brexit and the Capital Markets Union

If the UK were to leave the European Union, it will mean that it will also be outside the Capital Markets Union (CMU), when completed. The CMU is a set of measures designed to clear obstacles between companies and potential investors. The idea – in the words of the European Commission that created it – is “to mobilise capital and channel it to all companies, including SMEs, and infrastructure projects that need it to expand and create jobs”.
The EU economy is slightly bigger than that of the US, but its capital market is very different. Its equity market is about half the size of that of the US and its securitisation market is less than a quarter of the US.
Private finance is 70 per cent higher in the US despite the EU catching up in recent years.
At the moment the UK is an important part of the EU’s capital and financial markets. According to data from the Association for Financial Markets in Europe (AFME), The UK is home to 27 per cent of EU listed companies by market value, 40 per cent of the EU’s listed SME’s are listed on UK exchanges and 46 per cent of the EU’s equity capital is raised through UK capital markets.
But such interconnectivity might not continue if the UK were to be outside the common regulatory framework of the CMU.
Paul McGhee, Director of Strategy at AFME, in an interview with the FT suggests that “a Brexit would call into question the ability of investment banks to offer their services throughout Europe. This would certainly limit the ability of the UK market to act as a hub for raising capital”.
Jean-Pierre Mustier, partner at Tikehau Capital Advisor, stated that “the benefits of the initiatives under the Capital Market Union might only apply to EU countries, which will no doubt launch “charm” offensives to convince firms to relocate.”
While Umberto Marengo, Associate Fellow at the Institute of International Affairs, in a paper published on EUROPP, affirms that “as the undisputed financial centre in Europe, the UK is set to gain disproportionally from deeper capital market integration – if it remains in the EU”.

With a less developed capital market, EU firms have fewer opportunities to access finance and they end up relying on lending from banks. According to S&P Global Market Intelligence only about 10 per cent of US non-financial corporate lending was via banks last year, the proportion is over three times higher in Europe.
European households also rely on the banking sector more heavily then they do in the US. According to data from the Bank of International Settlements more than 50 per cent of the credit to household and non financial companies last year were from banks, compared to about half of that amount in the US. The proportion remained largely stable despite some decline recently.
One of the problem with an large exposure to bank-lending is that it might tighten in times of crisis, as in 2009 when many firms, particularly SMEs, had difficulty accessing finance.
Last year, about one in ten of SMEs in the Eurozone reported access to finance as the most pressing problem they faced, down from about 15 per cent in 2009. The proportion was about double for the micro firms than the large companies and was higher in some countries, including Spain where 27 per cent of SMEs suffered from poor access to finance in 2009.
Moreover, 44 per cent of EU SMEs did not get the full amount they needed and seven per cent had their application refused altogether. The proportion of refusal was much higher in France (13 per cent), Ireland, the Netherlands and Greece, where over 20 per cent of the applications were not fully met in 2015.
Increased investment would be good news for Europe, where the level of fixed capital formation – including buildings, infrastructure and equipment – collapsed after the crisis and are not yet showing signs of recovery, while in the US investment levels are already above pre-crisis levels.
The European Commission estimates that € 1.5-2tn of infrastructure investment will be needed by 2020. Of this, the energy sector is the largest component, with around €400bn on distribution networks and smart grids, another €200bn on transmission networks and storage and €500bn to upgrade and build new generation capacity. But the EC estimates do not cover the whole range of infrastructure. Water & sewage, waste management are not included, nor is social infrastructure or power generation.
Increased and diversified funding resources are expected to revamp economic growth in Europe. While the US has enjoyed a sustained recovery since the Great Recession, economic growth in Europe is weak, with slow productivity growth and pockets of very high unemployment rates.
Smaller countries and countries with less developed capital markets are likely to benefit more from the Capital Markets Union, according to Mr. McGhee , but UK companies will face huge uncertainties if they are out of it.

Thursday, 7 January 2016

Older workers lead employment growth in the Eurozone (lots of charts)

Older workers lead employment growth in the Eurozone (lots of charts)

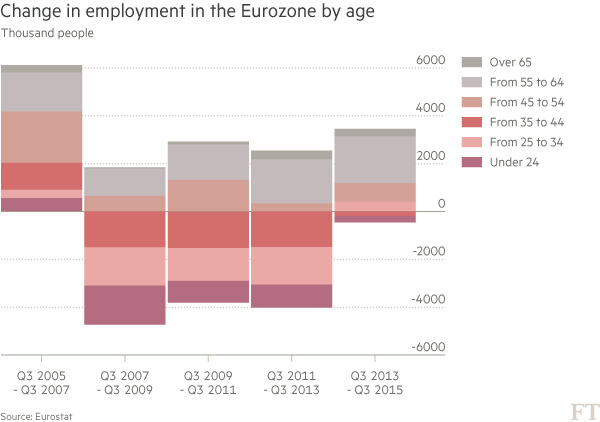
Employment is growing in the Eurozone. There were nearly 3 million more people in employment in the third quarter of 2015 than there were two years before.
However, of that 3 million around 2.3 million – or 75 per cent – were aged over 55, while the number of people in employment younger than 45 has continued to decrease.
The stronger employment performance of older workers is not new. Over the period of the crisis, jobs were lost among all age groups up to 45 years, but employment never stopped rising among the older population.
Italy lost about 1 million jobs – 5 per cent – from its employment peak in April 2008 to the trough in September 2013. Since then Italy has gained more than 400,000 jobs overall, but the number of people employed under the age of 55 has continued to decline.
In France employment expanded throughout the period analysed except for the two years to Q3 2009, but the growth was largely driven by older workers. In the two years to Q3 2015 employment for people aged under 45 expanded for the first time, but older workers still accounted for about two thirds of the net gain.
In Germany overall employment has been expanding since the start of 2010, but in contrast to France the number of people employed under the age of 45 never stopped falling. The 35 to 44 age group were hit particularly badly over the crisis and have yet to show any sign of recovery.
Spanish employment trends are different from those of the other major Eurozone countries. The employment contraction in Spain was massive. Nearly 3.8 million jobs – about 18 per cent of the workforce – were lost from August 2007 to February 2013. Younger workers were hit hardest, but there was also no growth in the employment of older workers. Since then employment has been expanding across nearly all age groups.
As with Spain, employment growth in the UK has not been concentrated among older workers. The employment performance of the group aged 45 to 55 showed an even stronger performance than the over 55 groups during and after the crisis. Those aged less than 35 were the ones hit more strongly by the crisis, but employment of these groups have grown faster since then. In the two years to Q3 2015 under-35s accounted for nearly half of all net employment growth.
But why have older workers led the employment recovery in the major Eurozone countries?
Structural reforms to pension and benefit system are an important part of the story. The trend could continue in France and Italy where, despite strong employment growth, fewer than 50 per cent of the population aged 55 to 64 were in the labour force in 2014, compared to 63 per cent in the UK.
Moreover, according to an ECB economic bulletin the strong employment trend among older people “may also reflect increased financial needs following losses in household wealth or income as a result of the financial crisis.”
Demographic effects – as the population ages – have had a larger effect in Germany where employment for the 35-44 age group contracted in terms of the number of jobs but remained fairly stable as a share of the population in that age group. However, both the absolute number of older workers and the proportion of the age group in employment have increased strongly since 2005.

But in France and more markedly in Italy the loss of jobs among younger employees and the lack of recovery have been even stronger trends than the changing demographic structure, and labour force participation rates have dropped among younger age groups over the last ten years.
High minimum wages and dual employment protection policies have beenmentioned as explanations for the lack of job opportunities for young people in both countries. In Italy, a poor vocational training system, high temporary contracts that lead to a lot of ‘churning’ and poor training of workers under fixed-term contracts all contribute to the poor employment performance among the youth.
The expansion of total employment in the Eurozone is good news, but the process now needs to involve young workers and those of prime working age.

Three reasons why we should stop focussing on manufacturing production

Valentina RomeiThree reasons why we should stop focussing on manufacturing production

The fortunes of the manufacturing sector regularly captures the headlines while service industries are relatively under-reported by the media. Taking the number of articles on FT.com since the start of 2013 on the performance of manufacturing or services, over 600 pieces reported the manufacturing purchasing managers’ indices, while services were covered by about half that number of entries. Half of those pieces reporting the manufacturing PMI did so without any mention of the services sector, while services are almost never reported on their own.
This under-reporting and poor consideration of the services sector contrasts with the reality of contemporary economies for three reasons:
First, the manufacturing sector accounts for a small proportion of advanced economies.
In the UK and in the US manufacturing accounts for only about 10 per cent of total output, while services make up for more than 75 per cent of their economies. The manufacturing share is not much higher in other advanced economies.
Manufacturing is more important in Germany – about 22 per cent of total output – but services still make up more than two thirds of the economy. Only developing economies have larger manufacturing sectors, but the proportion progressively declines with economic development.
Second: Services are driving economic recovery.
The Markit purchasing manager index for developed markets shows that services are expanding much more strongly than manufacturing.
And GDP figures confirm the strong reliance of many advanced economies on their services sector. Real gross value added of manufacturing activities grew by an annual rate of 2 per cent in the UK and 1 per cent in the EU last year. The same figure for professional services was 7 per cent in the UK and 3 per cent in the EU.
Service activities account for almost the totality of positive contributions to economic growth in the third quarter this year in the European Union. Construction had a negative impact on growth, while manufacturing activity – the most reported sector- had a negligible contribution.
This is not a peculiarity of advanced economies. Even in China services are theengine of economic growth and the country is starting a necessary re-balancing process towards service and consumer- led growth.
Third: the distinction between services and manufacturing is vanishing.
The distinction between manufacturing and services should clear, since the first involves a tangible product and the latter doesn’t. But how important is this tangible product in the value of manufacturing production? How much does the actual value of the leather and labour involved producing a Prada handbag weigh in its overall value compared with branding, design, advertising and retailing? The same question could be asked for the cereals you eat in the morning or your smartphone.
Services are used throughout the manufacturing process and the manufacturing value chain. Some services are needed early in the chain (e.g., research and development), some are needed at the end (retailing, maintenance and repair), and some are needed at every stage (telecommunications and financial services). Individual manufacturers often require a full spectrum of services.
More than one third of all input in manufacturing in advanced economies is business services, including transport, financial services, IT and others. The proportion is higher in advanced economies than in China, where “products” input have a larger weight in manufacturing production.
Food and beverages production and vehicles production are more service-intensive than other industries, particularly basic metal industries.
The above figures refer only to the services and products that are sourced externally, but a large part of services are actually produced within manufacturing companies. This is the case of all internal research and development, sales and marketing activities and post-sales support.
So why are we focussed on manufacturing production?
Partially it’s because of a long lasting belief that you can create value only by creating tangible goods. This is deep rooted in our society and it echoes the 18th century physiocrats’ obsession with agriculture. This group of French economists held that only agriculture – or ‘the productive sector’ – can produce value added. Only planting seeds would result in new products been produced, as opposed to manufacturing – the ‘sterile sector’ – where products changed form but nothing additional is created.
Services are not a ‘residual’ sector. They account for the majority of output in advanced economies and are usually the most dynamic part of the economy. They are also a major component of manufacturing production, possibly the one that determines its competitiveness.
It’s about time we give services the space and consideration they deserve.